
A purchasing tool for your tax conversation
2026 equipment planning. See the potential net cost.
A $24,000 qualifying deduction at an assumed 35% marginal rate illustrates $8,400 in tax savings and a $15,600 after-tax cost. Change the assumptions below and confirm the result with your tax adviser.
Illustration only. Eligibility, available deduction limits and your tax position determine the actual result.

2026 planning estimate
What could your after-tax cost be?
Use your own equipment budget and estimated marginal tax rate. This is an illustration, not a guaranteed deduction, refund or discount.
Assumes a $24,000 qualifying deduction at a 35% marginal rate.
Federal Section 179 estimate only. Tax classification, state treatment, other deductions, financing costs and recapture are not modeled. Ask your tax adviser to confirm eligibility.
What Section 179 can do in 2026
Section 179 may let an eligible business deduct qualifying equipment costs rather than recover them entirely through depreciation over time. For tax years beginning in 2026, the maximum deduction is $2,560,000, with the limit reduced when qualifying property placed in service exceeds $4,090,000. The business-income limitation and other eligibility rules still apply. IRS Publication 946 explains the limits and requirements.
Equipment eligibility is not automatic
A mortuary cooler, cot, lift or other equipment purchase must be evaluated under the applicable tax rules. Business use generally must exceed 50% for Section 179. The business-use percentage, property classification and available deduction limits affect the amount that may qualify. Buildings and their structural components are generally outside the ordinary equipment rule, so a walk-in enclosure or installation needs specific review rather than a blanket “100% write-off” promise. See IRS eligibility guidance.
Ready for use matters more than the order date
Property is placed in service when it is ready and available for its specific use. For a calendar-year taxpayer seeking a 2026 deduction, that means meeting the applicable placed-in-service requirements by December 31, 2026; another tax year can have a different year-end. Paying a deposit or receiving equipment alone does not establish that requirement. See the IRS placed-in-service definition.
Planning target: November 21. Treat this as a purchasing-planning target, not an installation guarantee. Ask us to confirm product availability, production, freight, site readiness and any installation work in writing. Do not book a tax deduction based on an unconfirmed delivery date.
Section 179 and bonus depreciation are different provisions
IRS guidance provides 100% special depreciation for certain qualified property acquired and placed in service after January 19, 2025. That is a separate provision, with its own rules, not a second deduction of the same equipment cost. This calculator models only a simplified Section 179 illustration and does not combine the two. Review Publication 946 with your adviser.
Build a useful year-end purchasing file
- Equipment: keep the selected model, configuration, itemized price and accessories together.
- Business use: confirm the ownership, intended use, entity and tax-year assumptions.
- Timing: document when equipment is installed, tested and ready for its intended use.
- Costs and limits: review other qualifying purchases, taxable business income and any state differences with your tax adviser.
Compare published factory-direct equipment pricing before estimating the after-tax cost. The tax illustration is not a discount, a rebate or a promise of a refund.
Current equipment to compare
Full equipment catalog →Open the selected listing for current equipment pricing and required options. Product links do not add equipment to cart automatically.

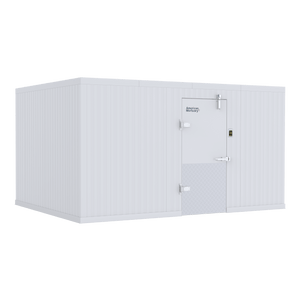
10x10 Walk-In Mortuary Cooler
Tax classification of the enclosure and installed components requires review.

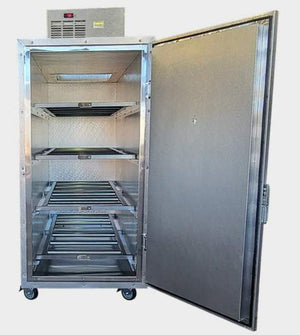
3 Body Upright Mortuary Cooler – Model 3B
Compare current equipment pricing and ask your adviser about the specific purchase.

Low Profile Powered Crematory Lift
Review eligible business use and placed-in-service timing for handling equipment.

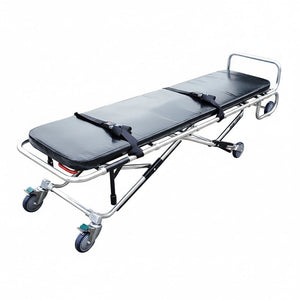
TITAN 1200XL Bariatric Mortuary Cot, 1,000 lb
Consider the complete annual equipment purchase plan with your adviser.
Bring the right equipment details to your adviser.
Build a written equipment request with the selected model, configuration and project timing. Confirm tax treatment separately with your qualified adviser.
The request builder includes purchasing-document and net-terms requests. Availability, credit approval and written terms apply.
Prepared with AI assistance from the AMC catalog and the cited public references. This is purchasing-planning information, not engineering approval, legal advice or a tax opinion. Confirm the selected configuration and project-specific requirements with the appropriate qualified professionals.

